Mark-to-Market Trading (Section 475(f)): The Ultimate Day Trader Tax Tool

In this article11 sections
A trader named Poppe lost a million dollars in 2007. That part isn't unusual for an active trader in a bad year. What happened next is the part worth learning from: he'd already earned Trader Tax Status, the IRS didn't dispute that, and he wanted that million-dollar loss treated as a fully deductible ordinary business loss under the mark-to-market election. The court agreed he was a real trader. It still ruled against him, because he couldn't produce a signed copy of his election statement or any proof it had ever been mailed. No Form 3115 on file either. His million-dollar loss got stuck under the same $3,000-a-year capital loss limit that applies to an ordinary investor, the exact outcome the election exists to prevent.
That's the real lesson of mark-to-market accounting: the tax benefit is enormous, but it lives entirely in the paperwork. Get the substance right and botch the filing, and you get none of it.
What is the mark-to-market election? Mark-to-market (MTM) is an accounting method under Section 475(f) that lets a qualifying trader treat every open position as sold at fair market value on the last trading day of the year, converting trading gains and losses from capital to ordinary. It's only available to traders who've already secured Trader Tax Status, and once validly made, it applies to every year going forward until formally revoked.
The Mechanic, Explained With an Analogy
Under the realization method everyone starts with by default, a gain or loss only exists the moment you actually sell. Mark-to-market changes that timing rule for anything you're still holding at year-end. Think of it like a landlord who has to report the current market value of every property they own on December 31st, whether or not they actually sold any of them that year, and then starts the new year as if they'd bought them all back at that same price. Nothing physically changes hands. The tax accounting just pretends it did.
For a genuine day trader who rarely carries a position overnight, this fictional year-end sale barely matters in practice, since almost everything already got realized during the year through actual trading. It matters far more for anyone who ends December holding open positions, since those get taxed as if closed even though they weren't.
The mechanic that actually does the work is simpler than the fictional sale: the election reclassifies your trading gains and losses from capital to ordinary. Every benefit and every drawback below flows from that single change.
Benefit One: The Wash Sale Rule Stops Applying
The wash sale rule only reaches capital assets. Once mark-to-market converts your trading securities into ordinary assets, the rule has nothing left to attach to. You can sell a losing position and buy it straight back the next morning without triggering a disallowed loss, something that routinely trips up active traders under the default capital gains method, especially anyone repeatedly trading the same handful of tickers.
Benefit Two: The $3,000 Ceiling Disappears
This is the exact benefit Poppe was fighting for and lost. Under the default method, a net capital loss beyond your gains is capped at a $3,000 annual deduction against other income, with the rest carried forward, sometimes for years. Under mark-to-market, your losses are ordinary losses, and ordinary losses aren't subject to that cap at all. They can offset an unlimited amount of other ordinary income in the year they happen, subject only to the separate excess business loss rule covered below.
Picture a trader who has one genuinely bad year: $50,000 in net trading losses. Under the default method, $3,000 of that offsets other income this year, and the remaining $47,000 sits in a carryforward, potentially useful someday, useless right now. Under a validly made mark-to-market election, the entire $50,000 offsets other ordinary income immediately. That's the difference between tax relief this year and a promise of tax relief eventually, if a future profitable year ever absorbs the carryforward.
What You Give Up: Ordinary Rates on Every Gain
Nothing here is one-directional. The same reclassification that frees up your losses also strips the discount off your gains. Long-term capital gains rates, 0%, 15%, or 20% depending on income, become permanently unavailable on anything covered by the election, regardless of how long you actually end up holding it.
For a trader who genuinely never holds past a few days, this costs nothing, since those gains were already short-term and taxed at ordinary rates under the default method anyway. It becomes a real cost the moment your strategy includes swing positions or the occasional long-term hold you were counting on for the discounted rate. Electing mark-to-market on a strategy like that can raise your total tax bill even while it's simultaneously fixing your wash sale problem.
There's also a separate ceiling worth knowing even with the $3,000 cap gone: the excess business loss rule under Section 461(l) still applies to very large losses. For 2026, that threshold sits at $256,000 for single filers and $512,000 for married couples filing jointly. Losses beyond that convert to a net operating loss carried forward rather than an immediate offset, so mark-to-market removes one wall, not every wall.
Should You Actually Elect This?
- Your situation
- Pure day trader, rarely holds overnight, has TTS
- Mark-to-market fit
- Strong fit. Gains were already short-term; wash sale and loss-cap relief cost nothing in exchange.
- Your situation
- Swing trader, regularly holds winners past a year
- Mark-to-market fit
- Poor fit. You'd convert discounted long-term gains into fully ordinary income.
- Your situation
- New strategy or scaling up, expecting a rough year or two
- Mark-to-market fit
- Worth considering. Full loss deductibility functions as insurance while you find your footing.
- Your situation
- Uncertain you can sustain TTS qualification long-term
- Mark-to-market fit
- Proceed carefully. The five-year lock-in covered below punishes an election you can't stick with.
- Your situation
- Mix of day trades and occasional long-term core positions
- Mark-to-market fit
- Depends on the split. Model both scenarios before electing; segregating the long-term holds into a separate account, discussed in the Trader Tax Status guide, also helps your TTS case independent of this decision.
| Your situation | Mark-to-market fit |
|---|---|
| Pure day trader, rarely holds overnight, has TTS | Strong fit. Gains were already short-term; wash sale and loss-cap relief cost nothing in exchange. |
| Swing trader, regularly holds winners past a year | Poor fit. You'd convert discounted long-term gains into fully ordinary income. |
| New strategy or scaling up, expecting a rough year or two | Worth considering. Full loss deductibility functions as insurance while you find your footing. |
| Uncertain you can sustain TTS qualification long-term | Proceed carefully. The five-year lock-in covered below punishes an election you can't stick with. |
| Mix of day trades and occasional long-term core positions | Depends on the split. Model both scenarios before electing; segregating the long-term holds into a separate account, discussed in the Trader Tax Status guide, also helps your TTS case independent of this decision. |
The QBI Deduction This Election Can Unlock
Straight capital gains never qualify for the 20% Qualified Business Income deduction under Section 199A. Ordinary income created by a valid mark-to-market election can. That's a genuine, if income-capped, additional upside to electing 475(f) beyond wash sale and loss-cap relief, covered in more depth, including the 2026 phase-out thresholds for specified service businesses like trading, in the Trader Tax Status guide.
How to Actually Make the Election Without Repeating Poppe's Mistake
Two separate filings are required, and missing either one, or failing to prove you made them, can cost you the entire benefit exactly as it cost Poppe his.
The election statement is due by the original filing deadline, without extensions, of the tax return for the year before the election takes effect. To have mark-to-market apply starting in 2026, an existing taxpayer needed to attach that statement to their timely filed 2025 return, or a timely extension request, by April 15, 2026. The statement itself has to say you're electing under Section 475(f), name the first effective tax year, and identify the trading business the election covers.
Form 3115, Application for Change in Accounting Method, is the second filing, attached to the return for the first year the election is actually in effect. This is precisely the form Poppe never filed. Skipping it, or failing to keep proof you filed it, is what turned his qualifying trader status into a worthless technicality.
Given what sank Poppe, treat documentation as part of the election itself, not paperwork to deal with later. Keep a signed copy of the election statement. Keep proof of mailing or, if filed electronically, confirmation of submission. Some CPAs recommend emailing yourself the relevant details the day you file, since email carries a timestamp that can help establish timing years later if the IRS ever asks. None of this is complicated. All of it is exactly what Poppe was missing.
A newly formed entity, one that wasn't required to file a return the prior year, gets a more flexible window: the election just needs to be documented in the entity's books and records within 75 days of its first day of business, then attached to that entity's first tax return, no Form 3115 required to establish it initially. This is the route some traders use after missing the April 15 deadline on their personal account, forming an entity later in the year and electing for it within the 75-day window instead.
Getting Out Is Harder Than Getting In
This is the part of mark-to-market that surprises even experienced traders, because the rules changed recently. Revenue Procedure 2025-23 significantly tightened revocation. Revoke within five years of making the election, and you need the non-automatic change procedure: a formal Form 3115 filing, explicit IRS Commissioner consent, and a user fee currently set at $13,225. Wait until five years have passed, and revocation reverts to the simpler automatic procedure, no fee, no advance approval.
The same five-year clock cuts the other direction too. Revoke, then want back in, and re-electing within five years of that revocation faces the same restricted, non-automatic process. This isn't a switch you flip back and forth as your strategy or market conditions shift.
Some traders use an informal workaround: deliberately trading enough to fail Trader Tax Status qualification, which suspends mark-to-market along with it without a formal revocation. Requalify for TTS later and the election automatically resumes. It's a real option, but it has a real cost: losing TTS also means losing your Schedule C expense deductions for however long you're out, and it creates messy accounting if the shift happens mid-year. A clean, formal revocation, even with the fee, is often the more defensible path, and given how much this election turns on documentation, "informal" is exactly the word that should give you pause.
Do Mark-to-Market Traders Pay Self-Employment Tax?
No. Even though the election converts trading gains to ordinary income, Congress specifically preserved the self-employment tax exclusion for trading activity under IRC Section 1402(a)(3)(A). The reclassification changes how the income is taxed at the federal level. It doesn't turn trading profit into earned income for Social Security and Medicare purposes. The full explanation is in the capital gains guide.
Editorial Verdict
For an active day trader who already has Trader Tax Status and rarely holds overnight, this election is close to a free upgrade: the gains were already taxed at ordinary rates, so there's nothing to lose on that side, while the wash sale and loss-cap relief solve two of the most persistent headaches in active trading. For a swing trader relying on long-term rates, or anyone unsure they can sustain TTS for years at a stretch, the trade-off deserves real modeling before electing, not a default yes.
Whichever way you land, the single most important lesson sits in Poppe's case, not in the tax mechanics themselves: a valid election that you can't prove you made is functionally the same as never having made it at all.
Frequently Asked Questions
What actually happened in the Poppe case, and why does it matter for this election specifically?
His $1 million loss ended up capped at the standard $3,000 annual deduction against other income, exactly the outcome mark-to-market exists to prevent. The case turned entirely on documentation, not on whether his trading activity qualified.
Key Takeaway: A substantively valid election with no proof behind it produces the same tax result as never electing at all.
What are the main benefits of the mark-to-market election?
Both come from the same source: the election reclassifies trading gains and losses as ordinary rather than capital. Ordinary losses can offset unlimited other income in the year they occur, subject to the separate excess business loss rule, and the wash sale rule, which only reaches capital assets, no longer applies.
Key Takeaway: Both benefits matter most to traders who rarely hold positions past a few days, since they have little long-term gain treatment to sacrifice in exchange.
What do you give up by electing mark-to-market?
For a pure day trader, this costs nothing, since those gains were headed for ordinary rates anyway. For a swing trader who regularly holds winners past a year, this can meaningfully raise the total tax bill even as it fixes wash sale and loss-cap problems.
Key Takeaway: Model your actual holding pattern before electing. This isn't a universal upgrade.
Who should elect mark-to-market accounting?
The election works best when your gains were already going to be taxed as short-term ordinary income anyway. Swing traders relying on long-term rates should model the tradeoff carefully first.
Key Takeaway: Match the election to your actual holding periods, not to a general desire to escape wash sale headaches.
Can I elect mark-to-market without Trader Tax Status?
Section 475(f) is written specifically for a person engaged in a trade or business as a trader in securities. Qualifying for that classification, covered in the Trader Tax Status guide, comes first, always.
Key Takeaway: There's no version of this election available before TTS is already established.
What is the deadline to elect mark-to-market accounting?
To take effect for a given year, the statement has to be attached to the prior year's timely filed return or extension request by that return's April deadline. There's no retroactive version for a year that's already ended.
Key Takeaway: Missing this deadline means waiting an entire additional year, and missing the follow-up paperwork can cost you the benefit even if you met the deadline, as Poppe's case shows.
How do I revoke a mark-to-market election?
Both paths require a revocation notification statement plus Form 3115, but the cost and approval requirement differ sharply depending on which side of the five-year mark you're on. Re-electing within five years of a revocation faces the same restricted process.
Key Takeaway: Treat this election as a five-year commitment at minimum, not a year-to-year choice.
Does mark-to-market income qualify for the QBI deduction?
This eligibility is capped by the specified-service-business phase-out that applies to trading income at higher taxable income levels, detailed in the Trader Tax Status guide.
Key Takeaway: For a profitable trader under the phase-out threshold, QBI is a real additional reason to consider this election beyond wash sale and loss-cap relief.
Do mark-to-market traders pay self-employment tax on their gains?
The reclassification changes how the income is taxed at the federal income tax level. It does not turn trading profit into earned income for Social Security and Medicare purposes.
Key Takeaway: Ordinary income treatment under mark-to-market is not the same thing as self-employment income, and the two get confused constantly.
What's the safest way to avoid ending up in Poppe's situation?
Poppe's downfall wasn't a disqualifying trading pattern. It was the complete absence of proof that a valid election had ever been made. That's an entirely preventable failure with basic recordkeeping.
Key Takeaway: Treat the paperwork trail as part of the election itself, not an afterthought you'll deal with if the IRS ever asks.
Disclaimer
Article Sources
- Poppe v. Commissioner, T.C. Memo. 2015-205 - the qualifying trader who lost ordinary loss treatment purely on documentation grounds
- IRS Topic 429, Traders in Securities - the election mechanics and the current Revenue Procedure 2025-23 revocation rules
- IRS Instructions for Form 3115, Application for Change in Accounting Method - the formal accounting method change process
- Cornell Law School, 26 U.S. Code Section 475 - the statutory text of the mark-to-market accounting method
- Cornell Law School, 26 U.S. Code Section 1402 - the self-employment tax exclusion that survives the ordinary-income conversion
- IRS: Qualified Business Income Deduction - the Section 199A framework that mark-to-market income can qualify under
Was this helpful?
Be the first to weigh in
Written by
Kazi Mezanur RahmanFounder, independent researcher, and editor of DayTradingToolkit. A one-person publication focused on risk-first trading education and documented tool research. He trades his own capital as a retail trader and combines personal market experience with systematic primary-source research.
Keep Reading
Day Trading Basics
Short-Term vs. Long-Term Capital Gains for Day Traders
Two traders can make an identical $10,000 profit and owe a meaningfully different tax bill, purely from how many days they held the position. Almost every day trade lands on the expensive side of that split. Here's the holding-period rule, the full 2026 bracket numbers, the netting process, and the self-employment tax myth that sends traders toward the wrong strategy.
Day Trading Basics
Trader Tax Status: What the Tax Court Cases Actually Show
Trader Tax Status is decided by judges reading your whole trading pattern, not a checklist. Endicott traded $7 million and lost. Nelson traded $33 million and lost. Here's what the actual case law shows, how to calculate your own holding period, and how to build a claim that survives a challenge.
Day Trading Basics
The Wash Sale Rule Explained: How to Avoid This Costly Trading Trap
A wash sale inside your IRA doesn't defer your loss, it destroys it permanently, and it can happen through an automatic contribution you forgot you set up. Here's the full 61-day mechanism, the real IRS ruling behind the IRA trap, and the current 2026 answer on crypto.
Day Trading Basics
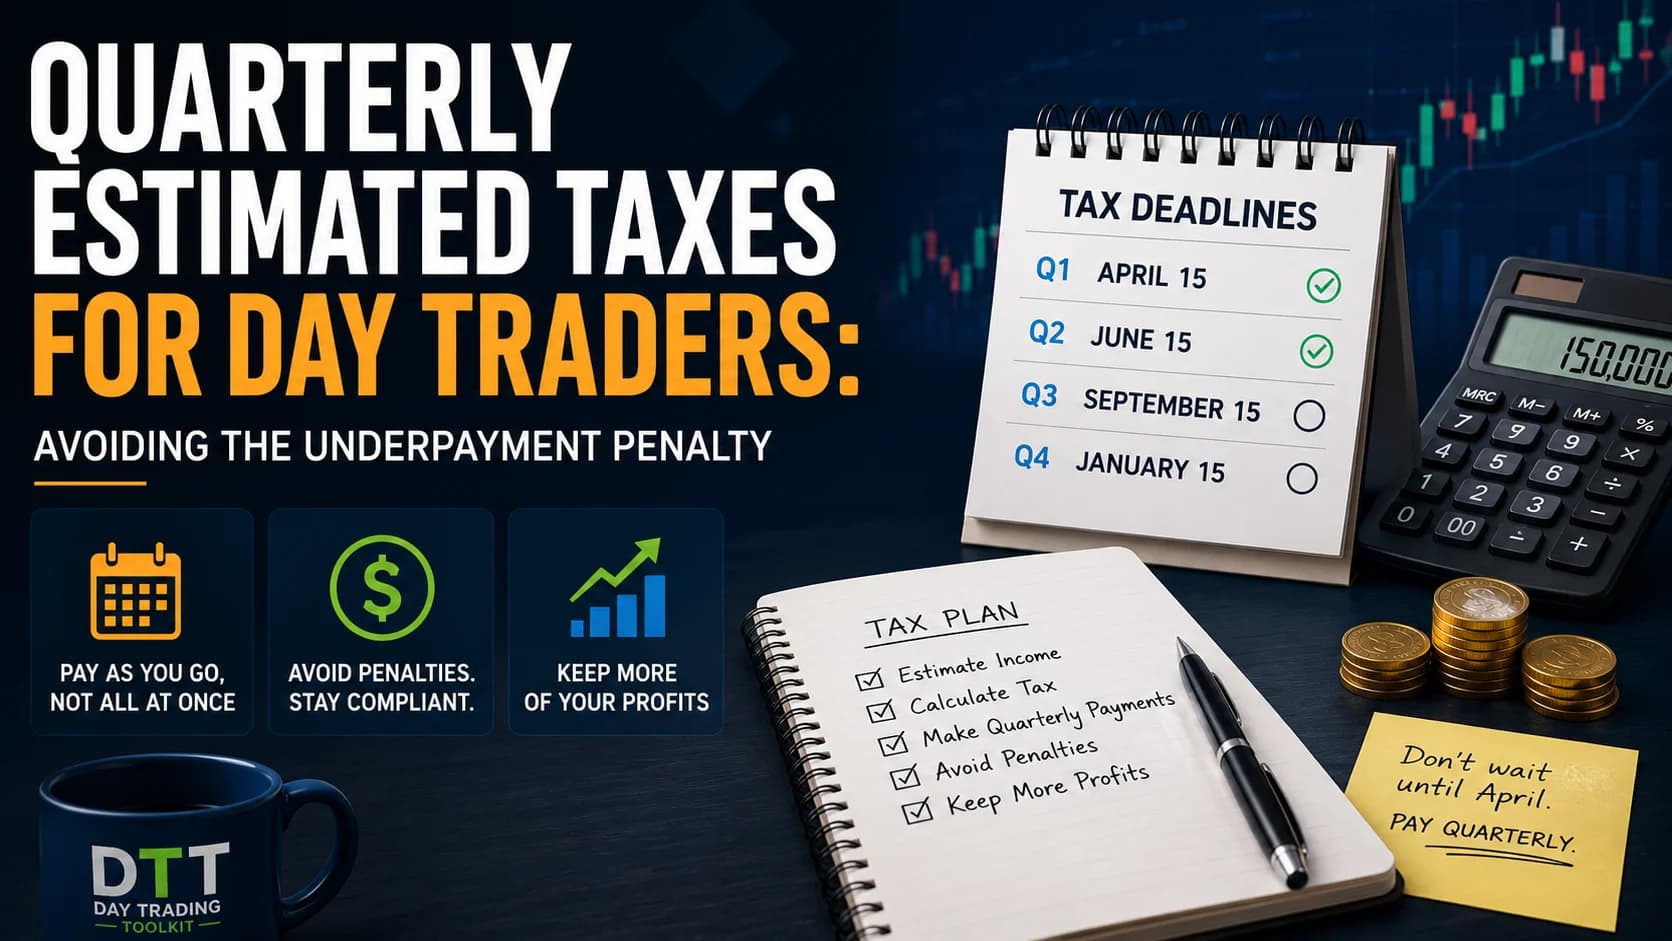
Quarterly Estimated Taxes for Day Traders: Avoiding the Underpayment Penalty
A trader has a rough nine months, then an incredible six-week run that makes the whole year profitable. He pays his full tax bill by April 15 and still gets a penalty notice, because the IRS calculates underpayment quarter by quarter, not against the annual total. Here's the safe harbor rules, the fix for lumpy trading income, and exactly when payments are due.
Comments
No comments yet. Be the first to share your thoughts.