LLC for Day Trading: Choosing the Right Business Structure to Optimize Taxes

In this article9 sections
Two profitable traders each form an S-Corp for a $150,000 trading year. The first reads generic small-business advice and pays himself a "reasonable market salary" of $70,000, the way a financial advisor or consultant would need to under standard S-Corp rules, and distributes the remaining $80,000. He owes $10,710 in combined payroll tax on that salary. The second works with a CPA who specializes in traders, who tells him something that sounds wrong at first: none of that $150,000 was ever going to be subject to self-employment tax in the first place, salary or no salary, entity or no entity. He pays himself just enough to fund his retirement plan the way he wants to, and saves several thousand dollars the first trader paid for nothing.
That's the single most misunderstood part of entity structuring for day traders, and it's the opposite of how S-Corps work for almost every other kind of small business. Getting this backwards is the most expensive mistake in this entire topic.
Do day traders need an LLC or S-Corp? No entity is required to trade or to claim Trader Tax Status. An entity becomes useful once you're consistently profitable, specifically because an S-Corp can manufacture the "earned income" that trading gains don't produce on their own, unlocking retirement plan contributions and a health insurance deduction that a sole proprietor trader can't access at all.
Why the Standard S-Corp Tax-Savings Story Doesn't Apply Here
For a typical small business, an S-Corp exists to solve one problem: without it, 100% of the owner's net business income would be subject to the 15.3% self-employment tax. Splitting that income into a modest salary (taxed) and larger distributions (not taxed for payroll purposes) is where the classic S-Corp savings come from.
That entire premise breaks down for a trader. Gains from the sale of a capital asset are excluded from self-employment income under IRC Section 1402(a)(3)(A), covered in full in the capital gains guide. That exclusion holds true whether you trade as an individual, a disregarded LLC, or through a partnership, and it survives even if you've elected Section 475(f) mark-to-market accounting, which converts your gains to ordinary income but doesn't touch the self-employment tax exclusion. In every one of those structures, 100% of your trading profit already escapes self-employment tax with zero entity required.
Form an S-Corp and pay yourself a salary anyway, and you're not protecting income from a tax it was already exempt from. You're creating brand new payroll tax liability, 15.3% combined, on whatever salary you choose to pay, where none existed before. That's the inversion most generic small-business content, and the previous version of this article, gets backwards.
What an S-Corp Actually Does for a Trader
If an S-Corp doesn't save you self-employment tax on trading gains, why do trader tax specialists recommend one at all? Because two specific, valuable tax benefits require "earned income," and trading gains, capital or ordinary, categorically don't qualify as earned income no matter how you structure the trading itself.
Retirement plan contributions. A Solo 401(k) contribution, whether the employee deferral or the employer profit-sharing piece, requires compensation from a trade or business. A sole proprietor or partnership trader has no mechanism to pay themselves wages at all, which means no earned income, which means no retirement plan contribution capacity from trading profits, full stop. An S-Corp can pay its owner a W-2 salary, and that salary is earned income, unlocking the plan entirely.
The health insurance premium deduction. The same earned-income requirement applies to the above-the-line self-employed health insurance deduction. Without W-2 wages from an S-Corp, a trader with no other job has no earned income against which to claim it.
Both benefits exist specifically to manufacture earned income where none would otherwise exist. Neither has anything to do with reducing self-employment tax on the trading gains themselves, since that tax was never owed in the first place.
Why "Reasonable Compensation" Works Differently Here
The IRS requires S-Corp owners generally to pay themselves reasonable compensation for services rendered, and most trader tax specialists point out that the policy reason behind that rule, preventing owners from underpaying themselves to dodge self-employment tax on income that would otherwise be fully taxed, simply doesn't apply to a trading company's investment income. A trading S-Corp's net income comes from capital gains or Section 475 ordinary income, neither of which was ever going to generate self-employment tax regardless of how much or how little the officer is paid.
The practical implication most trader tax CPAs draw from this: rather than benchmarking your salary against what a financial analyst or portfolio manager would earn, size it around how much earned income you actually need to unlock the retirement contribution and health insurance deduction you're after, and no more. This is a more aggressive, specialist position rather than an explicit bright-line IRS ruling written for this exact scenario, so it's worth having a CPA who works specifically with traders set and document your number rather than guessing.
Running the Actual Numbers for 2026
Take a trader who wants to maximize their Solo 401(k) contribution. For 2026, the employee elective deferral limit is $24,500 under age 50, and the employer profit-sharing side allows up to 25% of W-2 wages, with combined contributions capped at $72,000. A salary of exactly $24,500 unlocks the full employee deferral with the smallest possible payroll tax hit, $3,749 in combined FICA. Every additional dollar of salary beyond that buys 25 cents of additional profit-sharing room, at a cost of about 15.3 cents of payroll tax per dollar of salary, a real trade worth running the math on, but not a default reason to jump straight to a $70,000 "market rate" number the way non-trader small business advice would suggest.
Compare that to the opening example's $70,000 salary: $10,710 in payroll tax for access to more profit-sharing room, versus $3,749 for a salary sized specifically around the employee deferral limit. The right number depends entirely on how much total retirement contribution and health insurance deduction you're targeting for the year, not on what a comparable non-trading professional would earn.
The Other Real Benefits: Ring-Fencing and SALT
Beyond the earned-income mechanics, an S-Corp or partnership offers two further advantages worth knowing about, covered in more depth from the qualification side in the Trader Tax Status guide. Running all your active trading inside a dedicated entity keeps it cleanly separated from any personal long-term holdings, the same segregation principle that protected traders in several Tax Court cases discussed there. And in most states, a pass-through entity can elect to pay state income tax at the entity level, converting what would otherwise be a non-deductible state tax above the federal SALT cap into a deductible business expense, a workaround unavailable to sole proprietors.
The Entity Options, Briefly
Sole proprietorship is the default for anyone who hasn't formed anything. No cost, no filing, business expenses go on Schedule C, and trading gains flow through Schedule D or Form 4797 exactly as they would for anyone else. It cannot pay you a salary, which means no retirement plan access and no health insurance deduction from trading income, but for a trader under roughly $50,000 in net income, that limitation usually costs less than the compliance burden of anything more complex would.
A single-member LLC is a disregarded entity for tax purposes, taxed identically to a sole proprietor, with the added benefit of a legal liability shield. It's worth considering once you're using significant margin, have hired contractors, or simply want the liability separation, but it changes nothing about your tax picture.
A multi-member LLC taxed as a partnership, most commonly a spousal LLC, files its own return and issues K-1s, and can access the SALT workaround and ring-fencing benefits. It still cannot pay wages to partners, so it doesn't solve the earned-income problem.
An S-Corp is the structure that actually solves the earned-income problem, by electing S-Corp tax treatment for an LLC (Form 2553, filed within 75 days of formation for a new entity or by March 15 for an existing one). It requires running payroll, filing Form 1120-S, and maintaining real corporate formalities, meaningfully more compliance work than any of the above.
A C-Corp is almost never right for a trader. Corporate profits are taxed at 21%, and anything distributed to you gets taxed again personally, double taxation that only makes sense in narrow, high-income dual-entity structures most traders will never need.
When the Compliance Cost Actually Pays Off
Running an S-Corp costs real money: payroll processing, a more complex tax return, and ongoing bookkeeping typically run $2,500 to $7,500 a year combined depending on your state and whether you outsource the work. That cost has to be weighed against the actual benefits available, which, given everything above, come almost entirely from the retirement contribution and health insurance deduction, plus the SALT workaround if you're in a high-tax state, rather than from any payroll-tax-on-distributions savings.
A trader targeting a meaningful Solo 401(k) contribution and paying $15,000 to $20,000 a year in health insurance premiums can generate tax savings well into five figures even after the compliance cost. A trader with modest retirement goals, employer-provided health insurance through a spouse, and no SALT cap problem may find the S-Corp barely breaks even, or loses money, once the actual mechanics are run correctly rather than assumed.
Common Mistakes Worth Avoiding
Forming an entity before qualifying for Trader Tax Status accomplishes nothing, since the entity doesn't create TTS, your trading activity does. Forming an LLC in a low-tax state like Wyoming while actually living and trading from California or New York doesn't avoid your home state's tax either, since you'll still owe tax there under nexus rules, and you'll likely end up paying registration fees in both states for no benefit. And missing the 75-day window to file the S-Corp election after forming a new entity means waiting an entire additional year, since there's no informal way to backdate it.
Frequently Asked Questions
Do day traders need an LLC to trade?
An entity becomes useful once you're consistently profitable and want access to retirement plan contributions, a health insurance deduction, or liability protection, none of which require an entity to start trading in the first place.
Key Takeaway: Get profitable and confirm TTS qualification first. Entity formation is an optimization step, not a prerequisite.
Does an S-Corp save traders money on self-employment tax?
Forming an S-Corp and paying yourself a salary creates new payroll tax liability on that salary, since none existed on the underlying trading income to begin with. The classic S-Corp salary-versus-distribution savings that apply to other small businesses don't apply here.
Key Takeaway: An S-Corp doesn't protect trading income from a tax it was never going to owe.
Then why would a trader want an S-Corp at all?
Both benefits require compensation from a trade or business. A sole proprietor or partnership trader has no way to pay themselves wages, so trading profits alone can't fund a retirement plan or support the health insurance deduction. An S-Corp's W-2 salary solves that specific problem.
Key Takeaway: The value of an S-Corp for a trader comes from earned-income benefits, not from reducing tax on the trading gains themselves.
What salary should a trader pay themselves through an S-Corp?
Since the reasonable-compensation doctrine exists to prevent underpaying salary to dodge tax on income that would otherwise be self-employment-taxed, and trading income was never in that category, the usual market-rate benchmarking logic doesn't carry the same weight here.
Key Takeaway: Every dollar of salary costs roughly 15.3% in payroll tax with no offsetting self-employment tax savings, so pay only as much as your retirement and health insurance goals actually require.
How much can a trader contribute to a Solo 401(k) through an S-Corp?
The employee deferral only requires a salary at least equal to the deferral amount. The employer profit-sharing piece scales with salary, so a larger contribution target requires a correspondingly larger salary, and larger payroll tax cost.
Key Takeaway: Decide your target contribution first, then size the salary to match it, rather than picking a salary and seeing what falls out.
Can a sole proprietor trader contribute to a Solo 401(k) from trading income?
This is true even for a highly profitable sole proprietor trader with Trader Tax Status. Without an S-Corp salary or another source of earned income, like a separate job, there's no earned income to base a contribution on.
Key Takeaway: This specific limitation is the primary reason profitable traders consider forming an S-Corp at all.
Should I form my trading entity in a state like Wyoming or Nevada for the tax benefits?
You'll typically end up paying formation and registered agent fees in the low-tax state plus foreign-entity registration fees and taxes in your actual home state, more total cost for no tax benefit.
Key Takeaway: Form your entity in the state where you actually live and trade, in the vast majority of cases.
What's the deadline to elect S-Corp status for a new entity?
Missing this window means the entity is taxed under its default classification, disregarded for a single-member LLC or partnership for a multi-member LLC, for the entire year, with no informal way to backdate the election.
Key Takeaway: Set a calendar reminder the day you form the entity if S-Corp treatment is the plan.
Does forming an entity help with the wash sale rule or Trader Tax Status qualification?
The entity itself doesn't create TTS or eliminate wash sales. The mark-to-market election, available only after TTS qualification, is what actually removes wash sale exposure.
Key Takeaway: Use an entity for segregation and earned-income benefits, and the mark-to-market election for wash sale relief.
Is a C-Corp ever a good choice for a day trader?
The narrow exception is a sophisticated dual-entity structure used by very high income traders, generally well above $500,000 annually, and even then it requires specialist planning most traders will never need.
Key Takeaway: For the overwhelming majority of traders, an S-Corp accomplishes everything a C-Corp would, without the double taxation.
Disclaimer
Article Sources
- Cornell Law School, 26 U.S. Code Section 1402 - the statutory exclusion of capital asset gains from self-employment income
- IRS: S Corporation Compensation and Medical Insurance Issues - the reasonable compensation framework and health insurance premium mechanics
- IRS: One-Participant 401(k) Plans - Solo 401(k) contribution rules and the earned income requirement
- IRS Topic 429, Traders in Securities - the Trader Tax Status prerequisite for meaningful entity benefits
- IRS: Qualified Business Income Deduction - how W-2 wages paid by a trading S-Corp interact with the QBI wage limitation
Was this helpful?
Be the first to weigh in
Written by
Kazi Mezanur RahmanFounder, independent researcher, and editor of DayTradingToolkit. A one-person publication focused on risk-first trading education and documented tool research. He trades his own capital as a retail trader and combines personal market experience with systematic primary-source research.
Keep Reading
Day Trading Basics
Short-Term vs. Long-Term Capital Gains for Day Traders
Two traders can make an identical $10,000 profit and owe a meaningfully different tax bill, purely from how many days they held the position. Almost every day trade lands on the expensive side of that split. Here's the holding-period rule, the full 2026 bracket numbers, the netting process, and the self-employment tax myth that sends traders toward the wrong strategy.
Day Trading Basics
Trader Tax Status: What the Tax Court Cases Actually Show
Trader Tax Status is decided by judges reading your whole trading pattern, not a checklist. Endicott traded $7 million and lost. Nelson traded $33 million and lost. Here's what the actual case law shows, how to calculate your own holding period, and how to build a claim that survives a challenge.
Day Trading Basics
Mark-to-Market Trading (Section 475(f)): The Ultimate Day Trader Tax Tool
A trader named Poppe had a $1 million loss and a qualifying trading pattern, and still lost the mark-to-market tax treatment because he couldn't prove he'd properly filed the election. Here's how the election actually works, the trade-off table for deciding if it fits your trading style, and exactly how to avoid Poppe's mistake.
Day Trading Basics
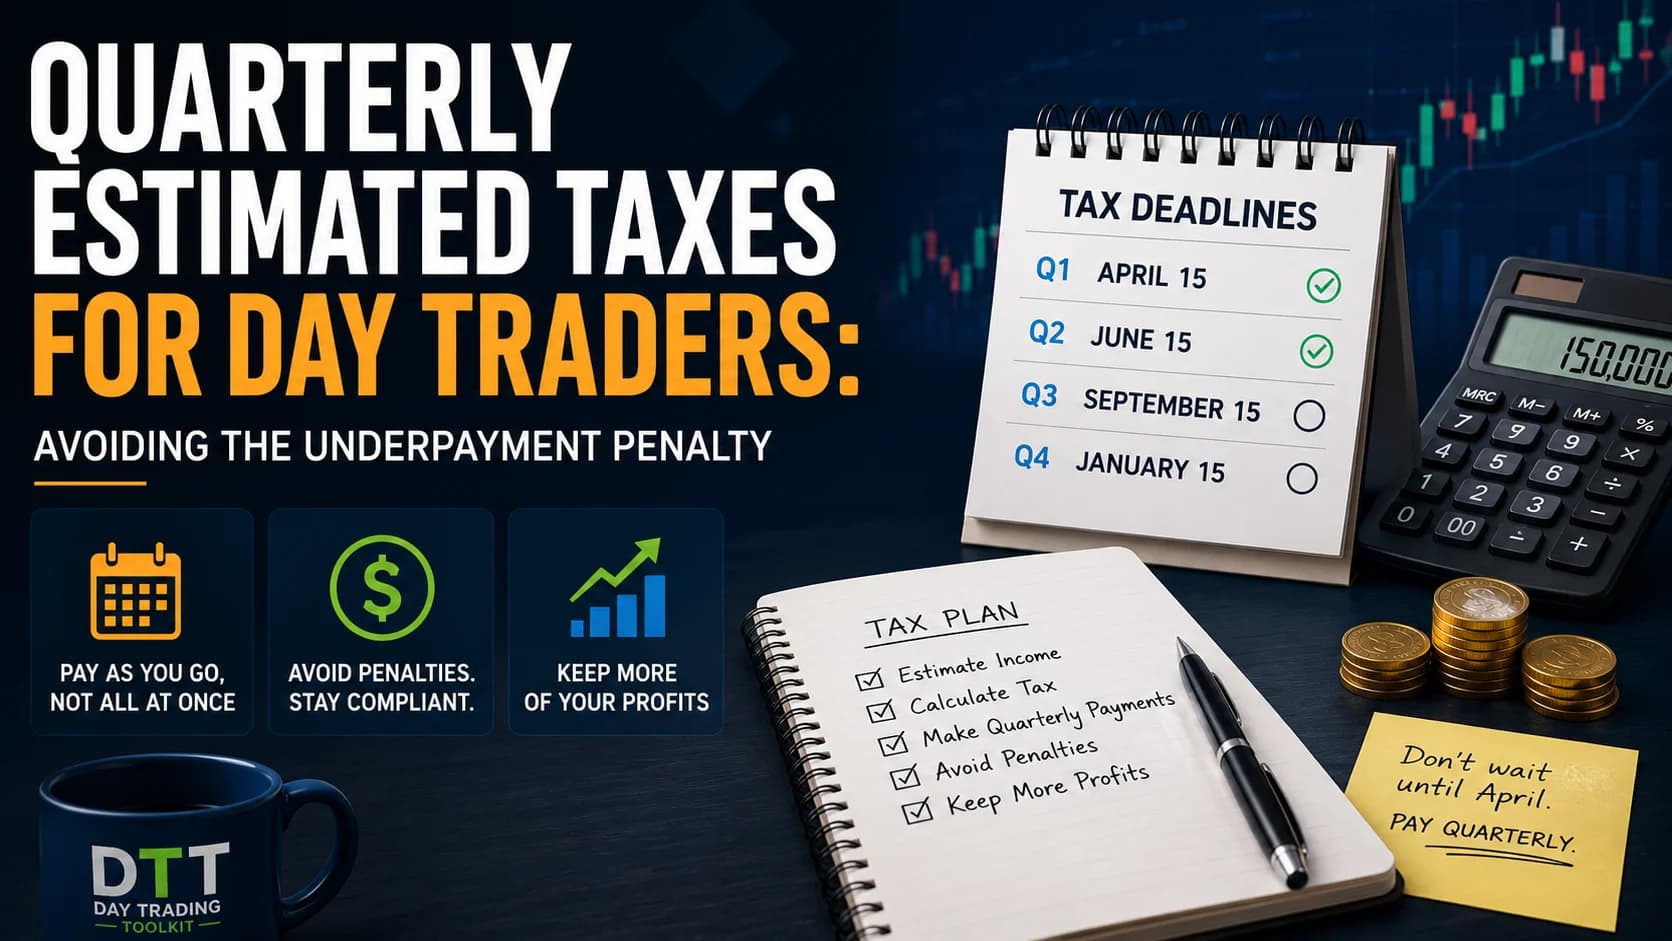
Quarterly Estimated Taxes for Day Traders: Avoiding the Underpayment Penalty
A trader has a rough nine months, then an incredible six-week run that makes the whole year profitable. He pays his full tax bill by April 15 and still gets a penalty notice, because the IRS calculates underpayment quarter by quarter, not against the annual total. Here's the safe harbor rules, the fix for lumpy trading income, and exactly when payments are due.
Comments
No comments yet. Be the first to share your thoughts.